Term Plan for Salaried
Buy Online
Term Insurance
This plan is designed for salaried individuals. If you continue as Non-Salaried you will be redirected to another page.
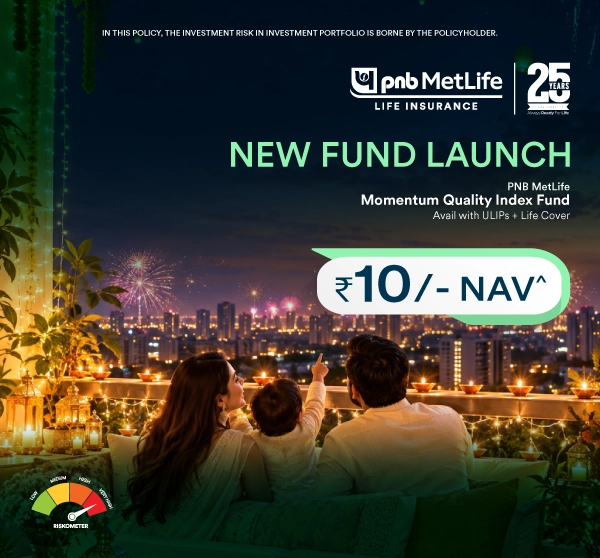
Quality for Resilience. Momentum for Growth.
Indian investors do not lack choices. The harder task is finding an approach that can participate in market trends without overlooking the financial strength of the companies behind those trends.
The PNB MetLife Momentum Quality Index Fund brings two investment factors together:
Think of it like building a strong cricket team.
Momentum is the in-form player who can accelerate the score. Quality is the dependable player with the technique and discipline to stay at the crease. A well-constructed team needs both, although even a strong team cannot guarantee the result of every match.
The PNB MetLife Momentum Quality Index Fund is a passive equity fund option that combines Momentum and Quality factors within eligible PNB MetLife ULIPs.
The fund follows the BSE 500 Momentum Quality Index (customized) and provides market-linked exposure within an eligible PNB MetLife Unit Linked Insurance Plan.
Important: This is not a mutual fund or a standalone investment product. Returns are market-linked, not guaranteed, and the investment risk is borne by the policyholder.
| Investor Question | Answer |
|---|---|
| What is the fund? | A passively managed equity fund option available through eligible PNB MetLife ULIPs |
| Which index does it track? | BSE 500 Momentum Quality Index (customized) |
| How are companies selected? | Using predefined Momentum and Quality criteria |
| What is the risk profile? | Very High |
| What is the SFIN? | ULIF04519/10/26MOMENTUMQL117 |
| When does the New Fund Launch begin? | 19 October 2026 |
| When does the New Fund Launch close? | 29 October 2026 |
| What is the NAV during the launch period? | ₹10, subject to the stated proposal and issuance conditions |
| How often is the index reviewed? | Quarterly |
| Who manages the fund? | Ankur Kulshreshtha |
| Which eligible ULIP is referenced in the source material? | PNB MetLife Smart Goal Ensuring Multiplier |
No. A ₹10 NAV does not make a fund cheaper or more likely to generate higher returns.
NAV is the per-unit value of a fund. A higher or lower starting NAV does not independently determine future investment performance
For example, ₹1 lakh invested at a ₹10 NAV purchases more units than ₹1 lakh invested at a higher NAV. However, the amount invested remains ₹1 lakh in either case. What matters after investment is the percentage movement in the NAV, along with portfolio performance, product structure and applicable charges.
For a detailed explanation, read ULIP NAV explained.
The ₹10 NAV applies to duly completed proposals received from 19 October to 29 October 2026 and issued on 30 October 2026. For policies issued after 30 October 2026, the prevailing NAV on the date of issuance will apply.
The future fund value will depend on factors such as:
₹10 is the starting NAV. It is not a discount, return promise or indicator of future performance.
Momentum identifies relative market strength. Quality applies a financial-characteristics filter. The strategy looks for companies that satisfy both sets of rules.
Markets rarely move in one straight line.
During some phases, companies displaying stronger share-price trends may lead the market. During other phases, attention may shift towards businesses displaying more stable financial characteristics.
Depending entirely on one factor can leave a portfolio more exposed when market leadership changes.
The Momentum Quality strategy seeks to avoid that one-sided approach.
The objective is not to chase the fastest-rising stock. It is to identify relative market strength while applying an additional Quality screen.
This creates a structured alternative to reacting to stock tips, headlines or short-term market noise.
The strategy offers the potential for:
These are characteristics of the strategy, not guaranteed outcomes.
Momentum shows what is moving. Quality examines whether the financial foundation meets the index criteria.
A return number may attract attention. The following conditions should shape the decision.
No.
The fund is market-linked, and its NAV can rise or fall according to the performance of the underlying portfolio. Historical performance of the benchmark does not guarantee the future performance of the fund.
The policyholder bears the investment risk associated with the investment portfolio.
ULIPs do not offer complete or partial liquidity during the first five years of the contract, subject to applicable regulatory provisions and the policy terms.
Read more about ULIP withdrawals and the five-year lock-in.
No.
The ₹10 NAV applies only when the stated proposal-receipt and policy-issuance conditions are met.
No.
Tax treatment depends on prevailing tax laws, qualifying conditions and the circumstances of the individual policyholder. Tax laws can change.
The PNB MetLife Momentum Quality Index Fund is a passively managed equity fund option available through eligible PNB MetLife ULIPs.
It uses the BSE 500 Momentum Quality Index (customized) as its benchmark. The customized index is created and maintained by BSE Indices for PNB MetLife India to meet applicable IRDAI investment norms.
If the term is unfamiliar, the guide what is an index fund? explains the basic concept of index-based investing.
Readers seeking a broader educational overview can also explore index funds: types and benefits.
Instead of depending entirely on discretionary stock selection, this strategy uses predefined criteria to identify eligible companies.
That makes the investment process:
Rules-based investing does not mean risk-free investing.
The strategy remains exposed to equity-market volatility, factor underperformance, concentration, trend reversals and tracking-related differences.
Momentum investing uses predefined criteria to identify companies displaying relatively stronger share-price trends over a specified period.
Think of two trains leaving the same station.
One train has already gathered speed and is moving strongly. Momentum investing attempts to identify such established movement using data and predefined rules.
This is different from selecting a company simply because it is popular on social media or because its share price rose over a few trading sessions.
Momentum may help the strategy:
Momentum can reverse quickly.
A company that displayed strong historical trends may decline because of:
Momentum identifies an existing trend. It cannot guarantee that the trend will continue.
Quality investing focuses on companies displaying selected financial characteristics, such as profitability, balance-sheet strength and efficient use of capital.
Think of buying a car.
Speed may attract attention, but a careful buyer will also check the engine, brakes and service record. Quality investing applies a similar second filter to the investment process.
Depending on the applicable index methodology, Quality characteristics may include:
Quality companies can also experience falling share prices.
A Quality filter cannot protect an investment from market volatility, changing valuations, business challenges or sector disruption.
Quality is a financial-characteristics filter, not a promise of capital protection.
| Factor | Momentum investing | Quality investing |
|---|---|---|
| Primary focus | Relative share-price trends | Selected financial characteristics |
| Role in the strategy | Identifies market strength | Adds a financial-quality filter |
| Potential advantage | Participation in established trends | Exposure to companies meeting Quality criteria |
| Key risk | Sudden trend reversal | Underperformance despite sound financial characteristics |
| Can it prevent losses? | No | No |
Neither factor is consistently better in every market environment.
Momentum and Quality can perform differently as market conditions change. Combining the factors reduces dependence on only one investment style, but it does not eliminate market risk.
At a high level, the customized-index strategy follows a structured process:
The fund seeks to replicate the customized benchmark, subject to applicable regulations, expenses, cash flows and tracking considerations.
The product source document states that the review frequency is quarterly.
The source material describes Momentum characteristics such as:
The source material describes Quality characteristics such as:
The reference index composition included exposure to sectors such as:
The sector composition and individual weights may change when the index is reviewed and rebalanced.
The reference composition should therefore be treated as a dated snapshot, not a permanent portfolio.
No.
Diversification can spread investment exposure across companies and sectors, but it cannot eliminate the possibility of investment loss.
The index rules may also result in higher exposure to particular sectors when more companies in those sectors meet the applicable selection criteria.
The 24.18% figure is the historical seven-year CAGR of the BSE 500 Momentum Quality Index (customized) as of 31 July 2026. It is not the historical return of the newly launched fund.
CAGR stands for compound annual growth rate. It represents the annualised rate at which the customized benchmark grew over the stated historical period.
The 24.18% figure represents:
It does not represent:
The benchmark has historical data. The newly launched fund does not inherit the benchmark’s performance history.
Based on the customized-index data in the source material, an illustrative contribution of ₹5,000 per month from 1 August 2016 would have reached ₹17,72,679 as of 31 July 2026.
| Illustrative contribution | Starting date | Historical index value at 31 July 2026 |
|---|---|---|
| ₹1,500 per month | 1 August 2016 | ₹5,31,804 |
| ₹2,500 per month | 1 August 2016 | ₹8,86,339 |
| ₹5,000 per month | 1 August 2016 | ₹17,72,679 |
| ₹10,000 per month | 1 August 2016 | ₹35,45,357 |
| ₹30,000 per month | 1 August 2016 | ₹1,06,36,071 |
The calculations are based on index data provided by BSE and exclude scheme-level expenses. They do not represent returns generated by the newly launched fund or guaranteed policy benefits.
The illustration shows how the customized index behaved during the selected historical period.
It does not tell an investor what the newly launched fund will deliver over the next ten years.
Past performance can explain history. It cannot write the future.
| Illustrative contribution | Starting date | Historical customized-index value on 31 July 2026 |
|---|---|---|
| ₹5,000 per month | 1 August 2016 | ₹17,72,679 |
| ₹5,000 per month | 1 August 2019 | ₹8,92,463 |
| ₹5,000 per month | 1 August 2021 | ₹4,57,071 |
| ₹5,000 per month | 1 August 2023 | ₹2,15,998 |
These are historical customized-index illustrations. Different starting dates produce different contribution periods and accumulated values. They are not actual returns earned by the newly launched fund.
| Illustrative annual contribution | Starting date | Historical customized-index value on 31 July 2026 |
|---|---|---|
| ₹1,00,000 per year | 1 August 2016 | ₹32,13,477 |
| ₹1,00,000 per year | 1 August 2019 | ₹16,49,839 |
| ₹1,00,000 per year | 1 August 2021 | ₹8,05,941 |
| ₹1,00,000 per year | 1 August 2023 | ₹3,79,751 |
| ₹2,50,000 per year | 1 August 2016 | ₹80,33,692 |
These figures are historical customized-index illustrations. They are not the performance of the newly launched fund or guaranteed policy values.
| Illustrative one-time contribution | Contribution date | Historical customized-index value on 31 July 2026 |
|---|---|---|
| ₹1,00,000 | 1 August 2016 | ₹6,43,920 |
| ₹2,50,000 | 1 August 2016 | ₹16,09,799 |
| ₹5,00,000 | 1 August 2016 | ₹32,19,598 |
The calculations exclude scheme-level expenses and should not be interpreted as actual or assured policyholder returns.
This fund option may be considered by eligible customers who:
Subject to suitability and the underlying policy terms, customers may evaluate the fund in the context of goals such as:
The fund may not suit customers who:
The right question is not “How much can this fund return?” The better question is “Does this ULIP and fund option fit my goal, risk capacity and time horizon?”
A Unit Linked Insurance Plan combines:
A portion of the premium supports the policy’s insurance benefits. The investible amount is allocated to the selected fund options after applicable charges and deductions.
The detailed guide what is ULIP and how does it work? explains the relationship between the premium, life cover, fund allocation and resulting policy value.
Before choosing a policy, customers should also consider the ULIP advantages and disadvantages rather than evaluating the decision only through its investment benefits.
The fund is available through eligible products such as the PNB MetLife Smart Goal Ensuring Multiplier, subject to the product’s eligibility conditions, available fund options and policy terms. This product as an individual, unit-linked, non-participating life insurance plan with UIN 117L139V05.
A fund is one component of a ULIP. The decision should be based on the complete insurance product, not only its investment strategy.
The ULIP provides life insurance protection according to the policy option selected and its applicable terms.
The actual benefit will depend on:
Customers should review the official documentation for the PNB MetLife Smart Goal Ensuring Multiplier before relying on a particular life-cover amount or policy benefit.
Fund switching may be available under the selected ULIP, subject to the terms and conditions of the product.
The allowable number of switches, eligible fund options, applicable charges and conditions should be checked in the relevant policy documents.
Switching should not be positioned as a guaranteed way to time the market, avoid losses or generate superior returns.
Unit-linked insurance products do not offer complete or partial liquidity during the first five years of the contract, subject to applicable regulations and policy terms.
The five-year period should be assessed before investing, particularly if the customer may need the money for an emergency or short-term goal.
The guide to ULIP withdrawals provides additional information about the lock-in and withdrawal considerations.
The fund may therefore not suit customers who:
Customers should review the official benefit illustration and policy documents before selecting the ULIP.
Depending on the product and selected option, applicable ULIP charges may include:
The exact charges may depend on factors such as:
These charges can affect the amount allocated to the fund and the resulting policy value.
Do not evaluate the policy only through the ₹10 NAV or the benchmark return. Evaluate the complete product, including insurance benefits, charges, lock-in and risks.
ULIP taxation does not work the same way in every situation.
Tax treatment depends on prevailing tax law and factors such as:
The product communication refers to zero tax on ULIP investment up to an annual premium of ₹2.5 lakh, subject to the applicable income-tax law and amendments made from time to time. It also instructs customers to consult a tax adviser.
The detailed guide to ULIP taxation provides further educational context. Customers should not treat general online information as personalised tax advice.
Tax benefits are subject to the provisions and conditions of prevailing tax laws. Tax laws are subject to change. Please consult a qualified tax adviser for guidance based on your circumstances.
GST and other applicable taxes or levies will apply in accordance with prevailing law.
The fund manager is Ankur Kulshreshtha.
Readers can visit the fund manager profile for additional information.
The presence of an experienced fund manager does not guarantee investment performance. Because this is a passively managed strategy, the fund seeks to replicate the customized benchmark, subject to applicable regulations, expenses, cash flows and tracking considerations.
The fund value can decline because of movements in the broader equity market.
Companies displaying strong historical market trends may experience a sudden price reversal.
Companies meeting the applicable Quality criteria can still underperform because of valuations, business developments or changing sector conditions.
Momentum and Quality can underperform other investment styles, separately or together, for extended periods.
The index rules may create higher exposure to particular companies or sectors at different points in time.
The fund’s performance may differ from the customized benchmark because of:
Complete or partial withdrawal is not available during the first five policy years, subject to applicable regulations and policy terms.
Changes in tax laws or insurance regulations can affect product benefits, fund operations and post-tax outcomes.
After the fund becomes operational, policyholders can use the official track fund value service to view available fund-value information.
Customers looking for a wider view of PNB MetLife’s investment funds may also visit all fund performance.
Fund-value and performance information should always be read with the applicable date, fund name, SFIN, expenses and risk disclosures.
The attached performance workbook classifies both the track-fund-value destination and the all-funds destination as non-indexable. These links can support customer navigation, but they should not be treated as primary organic-search landing pages unless the indexability settings change.
Customers researching index-based investment approaches may also explore the following PNB MetLife fund pages.
This related page supports research into a separate index strategy focused on the Momentum factor.
The Nifty 500 Momentum Index Fund and the PNB MetLife Momentum Quality Index Fund should not be treated as equivalent strategies. Their benchmarks, selection rules, portfolio compositions and factor exposures may differ.
The Multifactor Index Fund page supports readers who want to explore an approach involving multiple investment factors.
A multifactor strategy should not be assumed to use the same methodology, benchmark or allocation as the Momentum Quality Index Fund.
The Enhanced Value Index Fund page supports readers exploring a strategy built around a different investment factor.
Each fund should be evaluated independently according to its:
It is a market-linked fund option available through eligible PNB MetLife ULIPs. The fund follows a Momentum and Quality-based investment strategy benchmarked to the BSE 500 Momentum Quality Index (customized).
No.
It is a fund option available through eligible PNB MetLife ULIPs, not a standalone mutual fund.
No.
Returns are market-linked and depend on the performance of the portfolio. The policyholder bears the investment risk.
No.
₹10 is the initial per-unit NAV applicable under the stated launch conditions. It does not make the fund cheaper or more likely to generate higher returns.
Momentum investing uses predefined criteria to identify companies displaying relatively stronger share-price trends over a specified period.
Quality investing identifies companies displaying selected financial characteristics, which may include profitability, balance-sheet strength and efficient use of capital.
Momentum identifies relative market strength, while Quality adds a financial-characteristics filter.
Combining them reduces dependence on one factor, but it does not eliminate market risk.
The BSE 500 Momentum Quality Index has been customized for PNB MetLife India to meet applicable IRDAI investment norms.
The Segregated Fund Identification Number (SFIN) is ULIF04519/10/26MOMENTUMQL117.
The stated review frequency is quarterly.
ULIPs do not permit complete or partial withdrawal during the first five years, subject to applicable regulatory provisions and policy terms.
Fund switching may be available under the selected ULIP, subject to the policy’s terms and conditions.
No.
The 24.18% figure is the historical seven-year CAGR of the BSE 500 Momentum Quality Index (customized) as of 31 July 2026.
It is not the historical performance of the newly launched fund and does not predict future fund returns.
No.
Diversification can spread exposure across companies and sectors, but it cannot eliminate market risk or guarantee protection from investment loss.
Not necessarily.
Eligibility for tax benefits depends on prevailing tax laws, applicable qualifying conditions and the policyholder’s circumstances.
The fund may not suit customers who need short-term liquidity, guaranteed returns or capital protection.
It is intended for customers who can take a longer-term view and tolerate equity-market fluctuations.
The fund combines two familiar investment ideas:
Momentum seeks relative share-price strength. Quality adds a financial-characteristics screen. The eligible ULIP provides the associated life insurance framework.
Before deciding, customers can review:
The fund may be considered only after understanding three important realities:
Quality for resilience. Momentum for growth. Discipline for the long journey.
Before proceeding, review:
Consider the fund only when:
By submitting your details, you agree to PNB MetLife's Privacy Policy and authorize PNB MetLife and/or its authorized service providers to verify the above information and/or contact you to assist you with the policy purchase and/or servicing. You have the option to opt-out of this contact authorization by un-checking the box. The authorization provided by you herein will supersede all earlier authorizations/registrations made by you in this regard.
The investment risk in the investment portfolio is borne by the policyholder. ULIPs are different from traditional insurance products and are subject to market risks. Past performance of the benchmark/index is not indicative of future performance. Read all sales brochures and policy documents carefully before concluding a sale
This page/document is updated as on 16th October 2026.
THE UNIT-LINKED INSURANCE PRODUCTS DO NOT OFFER ANY LIQUIDITY DURING THE FIRST FIVE YEARS OF THE CONTRACT. THE POLICYHOLDER WILL NOT BE ABLE TO SURRENDER/WITHDRAW THE MONIES INVESTED IN UNIT-LINKED INSURANCE PRODUCTS COMPLETELY OR PARTIALLY TILL THE END OF THE FIFTH YEAR. T&C apply.
PNB MetLife Momentum Quality Index Fund (ULIF04519/10/26MOMENTUMQL117) is a passively managed fund with the BSE 500 Momentum Quality Index (customized) as its benchmark. Customized Index created and maintained by BSE Indices for PNB MetLife India to meet IRDAI Investment norms.
PNB MetLife Smart Goal Ensuring Multiplier (An Individual, Unit-Linked, Non-Participating, Life Insurance Plan UIN:117L139V05).
*Sum Assured is 10 times the Annual premium.
^NAV of Rs. 10/- will be applicable for duly completed proposals received from 19th to 29th October 2026 and issued on 30th October 2026. For policies issued after 30th October, the prevailing NAV on the day of issuance will be applicable. Past performance is not indicative of future performance. For more details on risk factors, terms & conditions, please read the sales brochure carefully before concluding a sale. PNB MetLife India Insurance Co. Ltd. IRDAI Reg. No. 117.
^^Invested vs Received illustrations (₹1 Lakh p.a., ₹5 Lakh one-time, ₹5,000 p.m.): The calculations are based on index data provided by BSE and exclude any scheme-level expenses. The above illustration shows the value accumulated as of 31st July 2026 (10-Year Period).
**24.18% return: Past 7-Year CAGR Return of BSE 500 Momentum Quality Index (Customized) as on 31st July 2026.
***Waiver of Premium + 0 LTCG Tax: Waiver of Premium on Death is applicable only under Income Assured Option provided the policy is in force. **Zero Tax on ULIP investment up to Rs.2.5 Lakhs Annual Premium, Tax benefits are as per Income Tax Laws in force & are subject to amendments made thereto from time to time. Please consult your tax consultant for more details. Goods and Services Tax (GST) shall be levied as per prevailing tax laws.
*^Claims Settlement Ratio: Individual claim settlement ratio as per latest annual audited figures reported to IRDAI for FY 2025-26.
PNB MetLife India Insurance Company Limited. Registered office address: Unit No. 701, 702 & 703, 7th Floor, West Wing, Raheja Towers, 26/27 M G Road, Bangalore -560001, Karnataka. IRDAI Registration number 117 | CIN U66010KA2001PLC028883. The marks "PNB" and "MetLife" are registered trademarks of Punjab National Bank and Metropolitan Life Insurance Company, respectively. PNB MetLife India Insurance Company Limited is a licensed user of these marks. Call us Toll-free at 1-800-425- 6969, Website: www.pnbmetlife.com, Email: indiaservice@pnbmetlife.co.in or Write to us: 1st Floor, Techniplex -1, Techniplex Complex, Off Veer Savarkar Flyover, Goregaon (West), Mumbai – 400062, Maharashtra.
AD-F/2026-27/298
| Beware of Spurious Phone Calls and Fictitious / Fraudulent Offers! IRDAI or its officials is not involved in activities like selling insurance policies, announcing bonus or investments of premium. Public receiving such phone calls are requested to lodge a police complaint. |
As your trusted life insurance partner, PNB MetLife covers COVID-19 claims. In the event of a death claim, please submit a signed claim form mentioning the policy number, a brief description of the insured event, and all other mandatory claim documents to the email addresses provided below. You may write to us at claimshelpdesk@pnbmetlife.co.in or indiaservice@pnbmetlife.co.in. For death claim intimation or any queries, you can also call us at 1800-425-6969 (for customers calling from within India only), Monday to Saturday, between 10:00 am and 7:00 pm
PNB MetLife Insurance, amongst the trusted Life Insurance companies in India, aims to provide a wide range of Life Insurance products that suits the needs of an individual at every stage of his life. Life Insurance Plans range from Term Life Insurance Plans, Term Plan, Protection Plans, Long Term Savings Plans , Retirement Plans & Child Education Plan.
 Get Trusted Advice