Term Plan for Salaried
Buy Online
Term Plan for Non-Salaried
Buy Online
Term Insurance
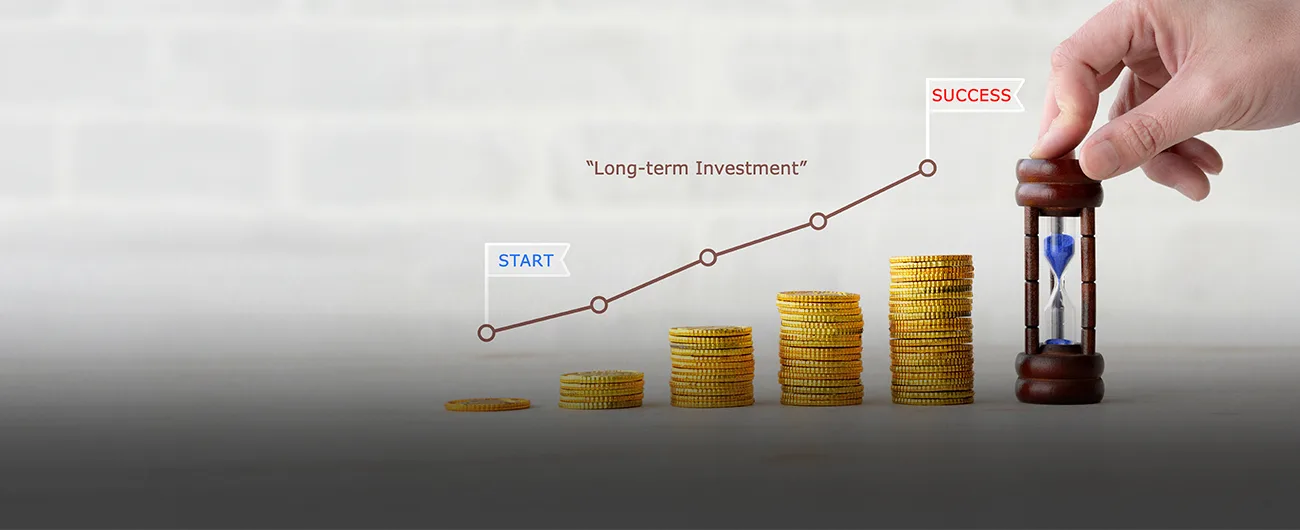
Money sitting idle in a locker or a regular savings account doesn't really grow. It just sits there, losing value slowly because of inflation. But money that is invested and left alone to grow, that's a different story altogether. This is where compounding investment comes into the picture, and honestly, it's one of the few things in finance that actually works in your favour the longer you wait.
By submitting your details, you agree to PNB MetLife's Privacy Policy and authorize PNB MetLife and/or its authorized service providers to verify the above information and/or contact you to assist you with the policy purchase and/or servicing. You have the option to opt-out of this contact authorization by un-checking the box. The authorization provided by you herein will supersede all earlier authorizations/registrations made by you in this regard.
Most people have heard the term "compounding" somewhere, maybe in a school textbook or from a relative talking about mutual funds. But very few actually understand how it works or how to use it to build real wealth. This guide breaks down everything you need to know about compounding investments.
Let's keep this simple. Compounding means you earn returns not only on the money you first put in, but also on whatever that money has already earned along the way. Your interest, in a sense, starts earning its own interest.
Picture a snowball rolling down a hill. Small at first. As it rolls, more snow clings to it, and that bigger snowball then picks up even more snow than before. By the time it reaches the bottom, it's turned into something far bigger than where it started. Money grows in much the same way once compounding gets going.
Say you put ₹1,00,000 into an investment earning 10% a year.
Notice the pattern. Each year brings in a little more than the last, even though the rate itself never changed from 10%. That extra bit of growth, quietly stacking up in the background, is compounding at work.
Now compare that to simple interest, which would hand you a flat ₹10,000 every year without fail, for as long as you stay invested. Stretch that comparison out to 20 or 30 years, and the gap between the two becomes huge.
The phrase "power of compounding" gets thrown around a lot, usually without anyone bothering to show what it actually looks like in numbers. So here's an attempt at that.
Take two people. Raghav and Simran.
At a 10% annual return, roughly, here's how things shake out:
| Investor | Investment Period | Total Amount Invested | Approx. Value at Age 60 |
|---|---|---|---|
| Raghav | Age 25-35 (10 years) | ₹6,00,000 | ₹1.9 crore approx |
| Simran | Age 35-60 (25 years) | ₹15,00,000 | ₹1.6 crore approx |
Raghav put in money for a much shorter stretch, less than half of what Simran contributed overall, and still ends up ahead. That's the real power of compounding on display. Time, it turns out, matters more than the size of your contribution.
Saying "compounding is good" and leaving it at that doesn't really tell you anything useful. What does it actually do for your money? Here are the real, practical benefits of compounding:
Here's something rarely spelled out clearly. Compounding needs time before it shows anything worth noticing. It isn't a shortcut, and anyone selling it as one is probably selling something else entirely.
A long-term investment approach is what gives compounding the room it needs to work. The first few years tend to look unremarkable on paper, a few thousand rupees added here and there. That's usually the exact point where people lose patience and quit, right before things start picking up.
| Duration Invested | Monthly Investment | Approx. Return Rate | Approx. Return Rate |
|---|---|---|---|
| 10 years | ₹5,000 | 10% | ₹10.3 lakh approx |
| 20 years | ₹5,000 | 10% | ₹38 lakh approx |
| 30 years | ₹5,000 | 10% | ₹1.1 crore approx |
Look at what happens between 10 and 20 years. Doubling the time doesn't just double the return, it roughly triples or quadruples it. Push it further, from 20 to 30 years, and the jump gets even more dramatic. This is what patience earns you.
A compound interest calculator does all this math instantly, sparing you the pen, paper, and patience it would otherwise take. Most insurance and investment company websites offer one free of charge.
What it usually asks for:
Enter those details and the calculator shows you the maturity value right away. It's genuinely useful for experimenting. What happens if you add ₹2,000 more each month? Change the number, see the result. Curious what five extra years would do to your final corpus? Adjust the time period and watch the figure jump.
Spending even ten minutes playing around with one of these calculators teaches more about how investments grow than several articles on the subject combined.
This is the part most people actually care about. Compounding is a concept. You still need somewhere real to put your money for it to actually work.
There are a few paths people in India tend to lean on when they're chasing long-term, compounding-driven growth. Here's a look at some of them.
These carry market risk, no doubt about it, but the growth potential over the long haul is hard to ignore. Returns move with the market, so patience matters here.
Safe. Backed by the government. Tax benefits come built in. The tradeoff is that returns sit lower compared to what equity can offer.
What makes these interesting is the combination, investment and life cover rolled into one. Your money grows in market-linked funds, and at the same time your family stays protected. A lot of people appreciate that ULIP plans handle both jobs, protection and wealth creation, so there's no need to juggle separate policies for each.
Building a savings habit isn't always easy, and that's really what these plans are designed around. Structure helps. Some long-term saving plans come with guaranteed benefits, others lean more market-linked, and either way they're aimed at people who find it hard to stay consistent on their own year after year.
Retirement is the whole point here. It's built for long-term compounding, and there are tax advantages that come along with it too.
Safety is the main draw with these. Returns, on the other hand, tend to stay modest, and inflation can sometimes outpace what you actually earn.
A lot of people accidentally sabotage their own compounding journey without even realising it.
Pulling out money in year 3 or 5, right when compounding is starting to pick up pace, is probably the biggest mistake investors make. The real magic happens in the later years.
When markets fall, panic sets in, and people stop their SIPs or withdraw entirely. But market dips, historically, have been some of the best times to keep investing, since you're buying more units at lower prices.
There's no shortcut here. Anything promising unusually high returns in a short time frame should raise a red flag. Real compounding takes years, not months.
Obsessing over daily market movement isn't necessary, but ignoring investments for years at a stretch isn't smart either. A yearly check-in, just to see whether the plan still fits current goals, is a reasonable habit to keep.
Compounding rewards three things squarely within anyone's control: patience, consistency, and time. Market movements and interest rate shifts are not. Starting early, even with a modest amount, gives money more room to grow into something meaningful. Waiting around for the "right time" or the "right amount" usually just costs years that compounding could have put to work.
Simple interest sticks to one number, the original amount, and calculates from that every single year. Nothing changes. Compound interest isn't like that. It keeps adding last year's interest into the mix, so the base you're earning on gets bigger and bigger as time passes.
There's no single answer here, honestly it depends on where you're putting your money. Equity-linked instruments can average out to higher returns if you stay in long enough. PPF, FDs, and similar options won't grow as fast, but what you lose in speed you gain in predictability.
Technically, yes. Interest added more frequently means your principal grows a bit faster over time. That said, the gap between monthly and yearly compounding tends to be small. What actually moves the needle is how long you stay invested, not how often the interest gets calculated.
Small amounts work fine. Put in a modest sum every month, stay consistent for fifteen or twenty years, and compounding does the heavy lifting on its own. The real mistake isn't starting small. It's not starting at all.
No, it stretches well beyond retirement. Saving for a child's education, a house, an emergency fund, any of these goals benefit from the same principle. Give the money time, and compounding takes care of the rest.
Most investment and insurance websites offer a free Compound Interest Calculator. Enter your amount, expected rate, and how long you plan to stay invested, and it will show you roughly what your money will turn into by the end.
The money already invested doesn't just vanish, it keeps growing on its own. What you do lose out on is the extra boost that would've come from continuing to add fresh contributions along the way.
For someone chasing market-linked growth while also wanting life cover, ULIPs can work well, particularly if the investment horizon stretches past ten years. Shorter timeframes tend to blunt the advantage.
Piyush Kataria, SEO Manager at PNB MetLife, is a seasoned digital marketing strategist with over a decade of experience in optimizing websites for search engines. His expertise extends to keyword research, content strategy, technical SEO, and link building, all of which have been instrumental in driving organic traffic growth at PNB MetLife. With a strong foundation in life insurance, Piyush leverages his industry knowledge to create targeted and effective SEO campaigns.

Sakshi Malhotra is a seasoned marketing professional associated with the Life Insurance industry since 2007. At PNB MetLife, she heads Digital Marketing and Direct to Customer line of business. She is responsible for driving effective customer engagement through the company’s website and social media channels. In addition, she drives customer online buying journeys to help them buy the right product.
Disclaimer:
The aforesaid article presents the view of an independent writer who is an expert on financial and insurance matters. PNB MetLife India Insurance Co. Ltd. doesn’t influence or support views of the writer of the article in any way. The article is informative in nature and PNB MetLife and/ or the writer of the article shall not be responsible for any direct/ indirect loss or liability or medical complications incurred by the reader for taking any decisions based on the contents and information given in article. Please consult your financial advisor/ insurance advisor/ health advisor before making any decision.
PNB MetLife India Insurance Company Limited
Registered office address: Unit No. 701, 702 & 703, 7th Floor, West Wing, Raheja Towers, 26/27 M G Road, Bangalore -560001, Karnataka
IRDAI Registration number 117 | CIN U66010KA2001PLC028883
For more details on risk factors, please read the sales brochure and the terms and conditions of the policy, carefully before concluding the sale.
Tax benefits are as per Income Tax Laws in force & are subject to amendments made thereto from time to time. Please consult your tax consultant for more details.
Goods and Services Tax (GST) if applicable, levied at prevailing rate subject to change from time to time.
The marks "PNB" and "MetLife" are registered trademarks of Punjab National Bank and Metropolitan Life Insurance Company, respectively. PNB MetLife India Insurance Company Limited is a licensed user of these marks.
Call us Toll-free at 1-800-425-6969, Website: www.pnbmetlife.com, Email: indiaservice@pnbmetlife.co.in or Write to us: 1st Floor, Techniplex -1, Techniplex Complex, Off Veer Savarkar Flyover, Goregaon (West), Mumbai – 400062, Maharashtra.
| Beware of Spurious Phone Calls and Fictitious / Fraudulent Offers! IRDAI or its officials is not involved in activities like selling insurance policies, announcing bonus or investments of premium. Public receiving such phone calls are requested to lodge a police complaint. |
As your trusted life insurance partner, PNB MetLife covers COVID-19 claims. In the event of a death claim, please submit a signed claim form mentioning the policy number, a brief description of the insured event, and all other mandatory claim documents to the email addresses provided below. You may write to us at claimshelpdesk@pnbmetlife.co.in or indiaservice@pnbmetlife.co.in. For death claim intimation or any queries, you can also call us at 1800-425-6969 (for customers calling from within India only), Monday to Saturday, between 10:00 am and 7:00 pm.
PNB MetLife Insurance, amongst the trusted Life Insurance companies in India, aims to provide a wide range of Life Insurance products that suits the needs of an individual at every stage of his life. Life Insurance Plans range from Term Life Insurance Plans, Term Plan, Protection Plans, Long Term Savings Plans , Retirement Plans & Child Education Plan.
 Get Trusted Advice
Ask khUshi

Hi! I’m khUshi. How can I help you?