Term Plan for Salaried
Buy Online
Term Plan for Non-Salaried
Buy Online
Term Insurance
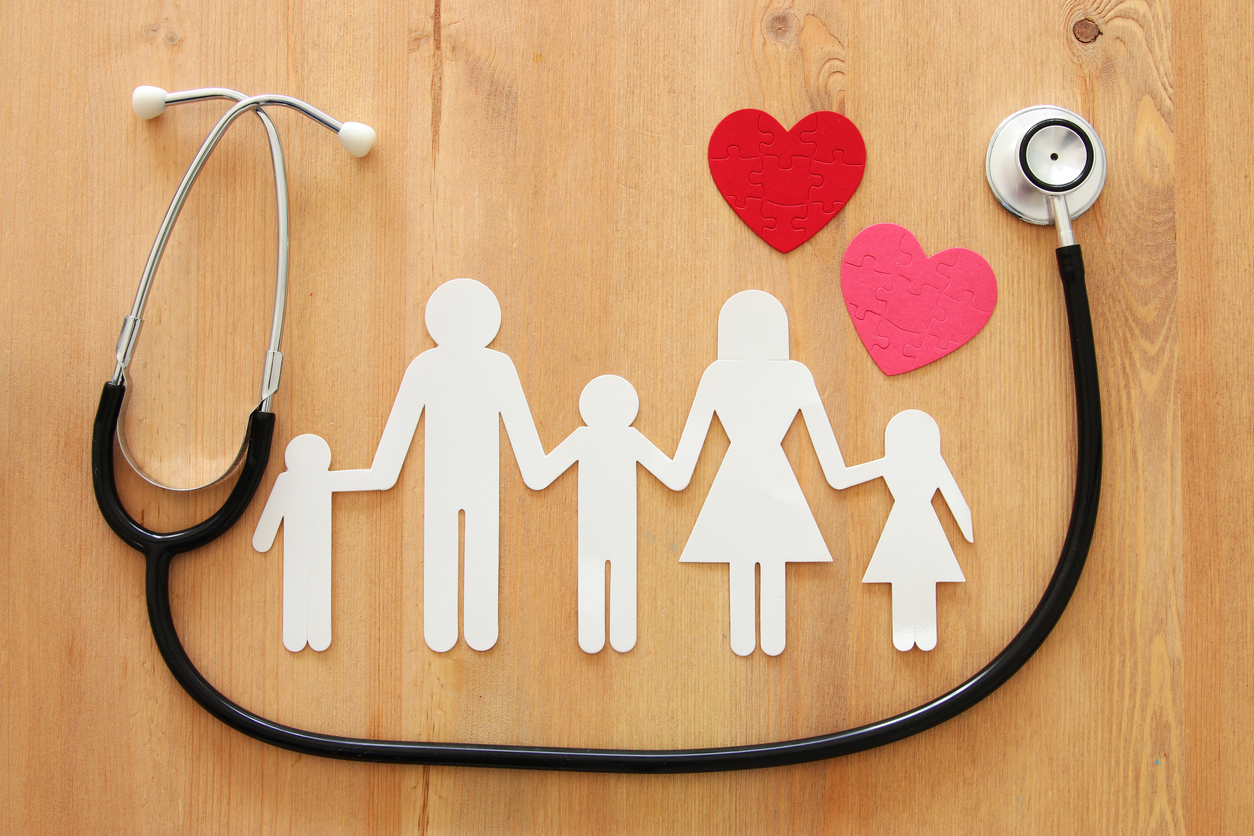
Medical bills don't send a warning text before they arrive. One day everything is fine, and the next day someone in the house is admitted for dengue, or an elderly parent needs a bypass surgery, and suddenly there's a bill running into lakhs. This is exactly where a family health insurance plan stops being "just another expense" and starts looking like one of the smartest financial moves a household can make.
By submitting your details, you agree to PNB MetLife's Privacy Policy and authorize PNB MetLife and/or its authorized service providers to verify the above information and/or contact you to assist you with the policy purchase and/or servicing. You have the option to opt-out of this contact authorization by un-checking the box. The authorization provided by you herein will supersede all earlier authorizations/registrations made by you in this regard.
This guide breaks down why buying a family health insurance plan should be treated as an investment and not a burden.
A family health insurance plan (also called a family floater plan) is a single policy that covers the medical expenses of your entire family under one sum insured. Instead of buying five separate policies for five family members, you buy one family health cover, and everyone shares that cover.
Say you buy a plan of ₹10 lakh for a family of four - you, your spouse, and two kids. If your child needs hospitalisation worth ₹3 lakh this year, the remaining ₹7 lakh is still available for the rest of the family for the rest of the year. That's the basic idea.
It's different from family medical insurance offered by some employers, which usually stops the day you leave the job. A personal plan stays with you, job or no job.
People often confuse insurance with a savings product. It isn't one, at least not in the traditional sense. You're not "investing" to get returns like you would with mutual funds. You're investing to protect the money you already have.
Here's the thing. Healthcare costs in India have been rising steadily every year, and a single major hospitalisation can wipe out years of savings in a matter of days. A family health insurance plan works like a shield around your bank account. That is what makes it prudent.
Think of it this way:
That difference alone justifies the premium you pay every year.
A Quick Cost Comparison
| Scenario | Without Family Health Cover | With Family Health Cover |
|---|---|---|
| Annual premium | ₹0 | ₹15,000 - ₹25,000 (approx, varies by age & sum insured) |
| Cost of a major surgery | ₹3-8 lakh out of pocket | Covered up to sum insured |
| Impact on savings | Heavy, sometimes savings wiped out | Minimal to none |
| Tax benefit under Section 80D | Not applicable | Applicable |
| Peace of mind | Low | High |
Numbers above are illustrative and will vary depending on your city, insurer, and the plan you choose. Always check current premium rates directly with the insurer before deciding.
Most people know that health insurance pays hospital bills. Fair enough, that's the obvious part. But the actual health insurance benefits go well beyond that one line.
You can read more about the full range of advantages here: health insurance benefits and features.
This is where most people go wrong. They pick a random number, like ₹5 lakh, because it "sounds like enough," without doing any actual math.
Here's a rough way to think about it. Your ideal health insurance coverage should factor in:
As a general starting point, for a family of four living in a metro city, a cover of ₹10-15 lakh is usually a sensible starting figure in today's environment. Smaller cities may need slightly less, but it's always safer to lean toward more cover than less, since medical inflation eats into your cushion over the years.
A common confusion is whether to buy one floater plan for everyone or separate plans for each person. Both have their place.
| Factor | Family Floater Plan | Individual Health Plan |
|---|---|---|
| Premium | Usually lower for the family combined | Higher when added up for each member |
| Sum insured | Shared among all members | Fixed and dedicated per person |
| Best for | Young families, kids | Elderly members or those with existing conditions |
| Claim flexibility | One member's big claim reduces cover for others | Doesn't affect other members' cover |
A practical approach many families follow is a floater for younger members and a separate individual cover for elderly parents, since older members tend to make more frequent claims which can quickly eat into a shared sum insured.
Not all policies are built the same, and picking the best family health insurance plan for your household needs a bit of homework. Here's a checklist worth going through before you sign up:
If you're unsure how to weigh these factors against each other, this resource walks through the process in more detail: choosing a health insurance plan that works for you.
A few patterns show up again and again, and they're worth flagging.
Worth clarifying this because people sometimes lump all insurance into one bucket. A family health insurance plan covers medical expenses. It has nothing to do with what happens to your family's finances if the primary earner passes away or becomes unable to earn.
That's a separate need altogether, covered by life insurance and specifically term insurance, which provide a lump sum to your family in case something happens to you. A financially secure household usually has both pieces in place - health cover for medical costs, and life or term cover for income protection. One without the other leaves a gap.
A family health insurance plan isn't something you buy and forget. It's a decision that protects your family's financial future the same way a term plan protects their income, or a fire extinguisher protects a house nobody plans to see on fire. You hope you never need it, but you'll be extremely glad it's there the one time you do.
If there's one takeaway from this entire guide, it's this: don't wait for a medical emergency to realise you should've bought a family health insurance plan last year. Buy it now, while premiums are lower and while the whole family is (hopefully) healthy.
There’s no direct answer. It depends heavily on your city and the health history of the members involved. As a rough starting point, families living in metros usually go for something in the ₹10-15 lakh range.
Yes, that's usually possible. Most insurers let you add a spouse or a newborn when the policy comes up for renewal, though the exact terms will vary from one insurer to another.
No. Almost every plan builds in a waiting period for this, typically somewhere between 2 and 4 years, before those conditions start getting covered.
Some do, some don't. When it's included, there's often a waiting period attached, anywhere from 9 months up to 2 years. Worth checking this one carefully if starting a family is on the cards.
Depends on whether your plan has a restoration benefit. If it does, the sum insured gets topped up automatically for the rest of the year, and this usually applies to unrelated illnesses.
It is, yes. Section 80D of the Income Tax Act covers this, and the exact limit depends on the age of whoever is insured under the policy.
Technically yes. But premiums climb fast once older members are added, so a lot of people end up choosing a separate plan just for their parents instead, which tends to be the more sensible route financially.
With cashless, the insurer deals directly with the hospital and settles the bill on your behalf. Reimbursement works the other way around. You pay upfront, then submit the documents, and the insurer pays you back once everything checks out.
Piyush Kataria, SEO Manager at PNB MetLife, is a seasoned digital marketing strategist with over a decade of experience in optimizing websites for search engines. His expertise extends to keyword research, content strategy, technical SEO, and link building, all of which have been instrumental in driving organic traffic growth at PNB MetLife. With a strong foundation in life insurance, Piyush leverages his industry knowledge to create targeted and effective SEO campaigns.

Sakshi Malhotra is a seasoned marketing professional associated with the Life Insurance industry since 2007. At PNB MetLife, she heads Digital Marketing and Direct to Customer line of business. She is responsible for driving effective customer engagement through the company’s website and social media channels. In addition, she drives customer online buying journeys to help them buy the right product.
Disclaimer:
The aforesaid article presents the view of an independent writer who is an expert on financial and insurance matters. PNB MetLife India Insurance Co. Ltd. doesn’t influence or support views of the writer of the article in any way. The article is informative in nature and PNB MetLife and/ or the writer of the article shall not be responsible for any direct/ indirect loss or liability or medical complications incurred by the reader for taking any decisions based on the contents and information given in article. Please consult your financial advisor/ insurance advisor/ health advisor before making any decision.
PNB MetLife India Insurance Company Limited
Registered office address: Unit No. 701, 702 & 703, 7th Floor, West Wing, Raheja Towers, 26/27 M G Road, Bangalore -560001, Karnataka
IRDAI Registration number 117 | CIN U66010KA2001PLC028883
For more details on risk factors, please read the sales brochure and the terms and conditions of the policy, carefully before concluding the sale.
Tax benefits are as per Income Tax Laws in force & are subject to amendments made thereto from time to time. Please consult your tax consultant for more details.
Goods and Services Tax (GST) if applicable, levied at prevailing rate subject to change from time to time.
The marks "PNB" and "MetLife" are registered trademarks of Punjab National Bank and Metropolitan Life Insurance Company, respectively. PNB MetLife India Insurance Company Limited is a licensed user of these marks.
Call us Toll-free at 1-800-425-6969, Website: www.pnbmetlife.com, Email: indiaservice@pnbmetlife.co.in or Write to us: 1st Floor, Techniplex -1, Techniplex Complex, Off Veer Savarkar Flyover, Goregaon (West), Mumbai – 400062, Maharashtra.
| Beware of Spurious Phone Calls and Fictitious / Fraudulent Offers! IRDAI or its officials is not involved in activities like selling insurance policies, announcing bonus or investments of premium. Public receiving such phone calls are requested to lodge a police complaint. |
As your trusted life insurance partner, PNB MetLife is with you amidst the current COVID-19 outbreak. Our policies also cover COVID-19 Claims. In case of a Death Claim, kindly submit the signed Claim Intimation Letter mentioning the policy number, brief of the insured event and other claim documents on the email mentioned herewith. Please write-in to us at claimshelpdesk@pnbmetlife.co.in or indiaservice@pnbmetlife.co.in. You can also call us on 1800-425-6969 for death claims intimations and for any queries on Monday - Saturday between 10:00 am - 7:00 pm.
PNB MetLife Insurance, amongst the trusted Life Insurance companies in India, aims to provide a wide range of Life Insurance products that suits the needs of an individual at every stage of his life. Life Insurance Plans range from Term Life Insurance Plans, Term Plan, Protection Plans, Long Term Savings Plans , Retirement Plans & Child Education Plan.
 Get Trusted Advice
Ask khUshi

Hi! I’m khUshi. How can I help you?